والر میخواهد مردم را «شوکهکننده» کند: مقام تندروی Fed مجدداً خواستار افزایش ۵۰ واحدپایهای نرخ بهره شد، در حالی که بازار از قیمتگذاری آن خودداری میکند
والر میخواهد مردم را «شوکهکننده» کند: مقام تندروی Fed مجدداً خواستار افزایش ۵۰ واحدپایهای نرخ بهره شد، در حالی که بازار از قیمتگذاری آن خودداری میکند. او برگشته است. هشت روز پس از تهدید به افزایش ۵۰ واحد پایهای نرخ بهره چند ساعت پیش از انتشار شاخص قیمت مصرفکننده (CPI)، کریس والر، از اعضای شورای حکام Fed، امروز صبح در CNBC حضور یافت و دوباره این حرف را تکرار کرد: تورم در مسیر اشتباهی حرکت میکند، در حال گسترش است و سیاستگذاران باید افزایش نیم درصدی را در تصمیمگیری ۹ دسامبر بررسی کنند. و فقط در صورتی که کسی...
Waller Wants To "Shock" People: Fed Hawk Reprises 50bps Call As Market Refuses To Price It He's back.
Eight days after threatening a 50bps hike hours before CPI , Fed Governor Chris Waller went on CNBC this morning and did it again: inflation is headed in the wrong direction, it is broadening, and policymakers should consider a half-point increase at the Dec. 9 decision . And just in case anyone thought he was bluffing, he told CNBC's Steve Liesman that " You might need to, like, shock people ."
Fed Governor Christopher Waller on how he's weighing the idea of votes for 25 basis-point hikes versus a vote for a larger, 50 basis-point hike. https://t.co/FnYcJ6zm51 pic.twitter.com/faVui1S0zr
— Squawk Box (@SquawkCNBC) November 18, 2026 The 2-year yield promptly erased a 2.5bp drop and rose as much as 2.8bp to 4.83%, while the 10Y spiked to a session high of 5.13% before fading back to 5.09%. And yet, with OIS still pricing a full quarter-point hike plus just ~3bps extra, the market puts the odds of Waller getting his way at roughly 10% . Which raises two questions: how far is the market from pricing it, and what happens to the AI bid and a long end already sitting at 5.1% if he does.
The case Waller laid out was less about the headline and more about breadth. By his count, roughly 70% of the items in the core services basket are now rising by more than 3% , a sign that the inflation impulse has long since escaped the energy shock (so much for "transitory pass-through"). Annualized, he said, inflation is heading toward 3.5%.
What seems to worry him most is pricing power: companies increasingly believe consumers are resilient enough to swallow price increases of 3% or more, and so the Fed may need to "shock" people out of thinking 3% is the new normal . Waller also said the Fed may have to take back all three of last year's "insurance" cuts, and maybe more. Insurance, as it turns out, against the wrong risk.
He did offer an alternative: hike 25bps in December and explicitly signal another move in January. The catch, as CNBC noted, is that this runs against how Chair Warsh likes to communicate (i.e., not pre-committing). Put differently, Waller is telling his boss: either give me 50 now, or give me forward guidance he doesn't want to give . Either way it's 50bps over two meetings.
Regular readers will recall that the London version of Waller put it like this on Nov 10, at the BoE Watchers conference, conditioning a 50bp move on October core CPI printing around 0.3% or higher:
In that case, I believe a 50 basis point hike in the policy rate should be considered at the December meeting. Hiking only 25 basis points would put our credibility at risk, a risk I am not eager to take.
Core CPI then printed 0.3% hours later (0.297% unrounded, so the threshold was met by the grace of rounding), odds of a 50bps hike jumped to about 14% , and ZH tweeted the "hawkish panic" in real time. Then the softer PPI trimmed those bets , and as we noted last week, none of Waller's colleagues joined him in openly backing 50.
That hasn't changed. Per Goldman's US economics team (Mericle), the closest thing to a response came from the New York Fed's John Williams, who said Tuesday: " I don't think the situation calls for dramatic action ". Williams also argued the October core print reflected a continuation, not a broadening, of tariff and energy passthrough, which is the polar opposite of Waller's "spreading out" diagnosis (and since both vote, someone is going to be disappointed). Meanwhile, St. Louis Fed's Musalem sees several increases by spring.
For those keeping score, this is the same Waller who flipped dovish in early September and sent everything ripping. Ten weeks later he wants to shock the public. Data dependence at its finest.
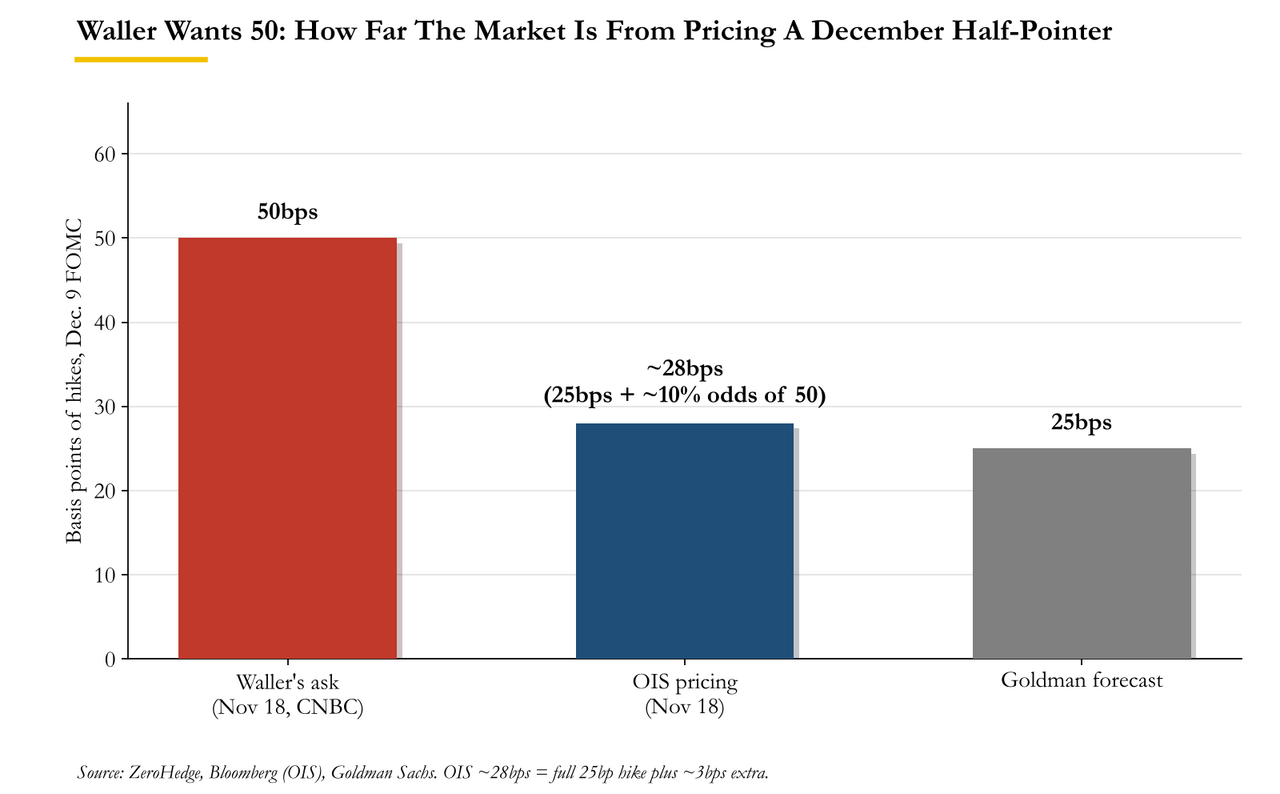
Short answer: about 22bps. Waller wants 50; OIS prices ~28bps for Dec. 9 (a done-deal 25bps plus a ~10% chance of the larger move), and Goldman's own forecast is a plain-vanilla 25bps .
The pricing has actually come off the boil: the December contract spiked to roughly 29bps right after CPI and had faded to ~25.8bps by Tuesday's close, per Goldman's Marquee chart (chart source GS FICC) . More interesting is what's behind it: another ~17bps is priced for January and ~17bps for March, or roughly 60bps of hikes through the spring (napkin math, assuming the pricing is cumulative per meeting).
Goldman's Mericle reads the October FOMC as a compromise to hike every other meeting, and after last week's CPI the bank added a third 25bp hike in March 2027, after a second one in December ( full note available to pro subs ). In other words, the street has the destination right and is arguing about the speed , which is exactly what Waller's "25 plus a January signal" option is about.
Here is the awkward timing: Waller's hawkish encore landed just as Nvidia's beat-and-raise was supposed to rescue a battered tech complex ahead of today's must-price Anthropic IPO. Goldman's Rich Privorotsky summed up the Nvidia print: " The spending isn’t stopping ". NDX had been re-testing its local lows into the print, per Goldman's Mark Flood , and futures were up ~0.3% this morning before Waller dented the mood, with gold's slide accelerating to below $3,800 , the lowest since Sept 2025.
The problem for the AI trade is that it no longer runs on cash flow. As we have been warning since last October, AI is now a debt bubble too , and a Fed that front-loads hikes raises the cost of every dollar of that debt just as Apollo's CEO talks about an $8 trillion buildout bill. (Waller, for his part, said concerns about AI financing are limited to the banks. Maybe.)
As for the long end, the 10Y was at 5.10% this morning per Goldman's desk, and the plumbing isn't helping: Tuesday's long-end Treasury buyback used only about 20% of announced capacity ($1.18BN accepted), versus the full $6BN in the previous operation . A 50bp hike would likely mean a bear flattener at first, with the front end doing the heavy lifting. Then again, with the 30-year mortgage rate at 7.35% (MBA) and building permits collapsing 7.4%, below every single forecast , a long end at 5.1% is already doing a fair bit of tightening on Waller's behalf.
Next up are the FOMC minutes at 2pm, where Goldman will be looking for the assumptions behind participants' outlooks and their views of the balance of risks. Since the October meeting, the inflation and labor data have, on net, come in firmer than expected, so the minutes will probably read stale on arrival.
Our take: Waller probably doesn't get his 50 in December (November CPI lands on Dec. 10, the day after the decision, and Williams isn't there yet). But he very likely gets the next best thing: a December hike paired with a January signal. Which means the real mispricing sits in the ~17bps priced for January , far more than in the 10% odds of 50 for December... along with a long end at 5.1% that hasn't fully done the math yet.
Much more in Goldman's Fed preview note , available to pro subs .
منبع: ZeroHedge — متن کامل از فید رسمی منبع، با ترجمهی ماشینی عنوان و خلاصه
گفتوگو