رویدادهای کلیدی این هفته شلوغ: درآمدهای NVDA، عرضه اولیه عمومی Anthropic، خردهفروشی، نشست ایالات متحده و چین، سخنرانیهای فراوان Fed و خیلی موارد دیگر
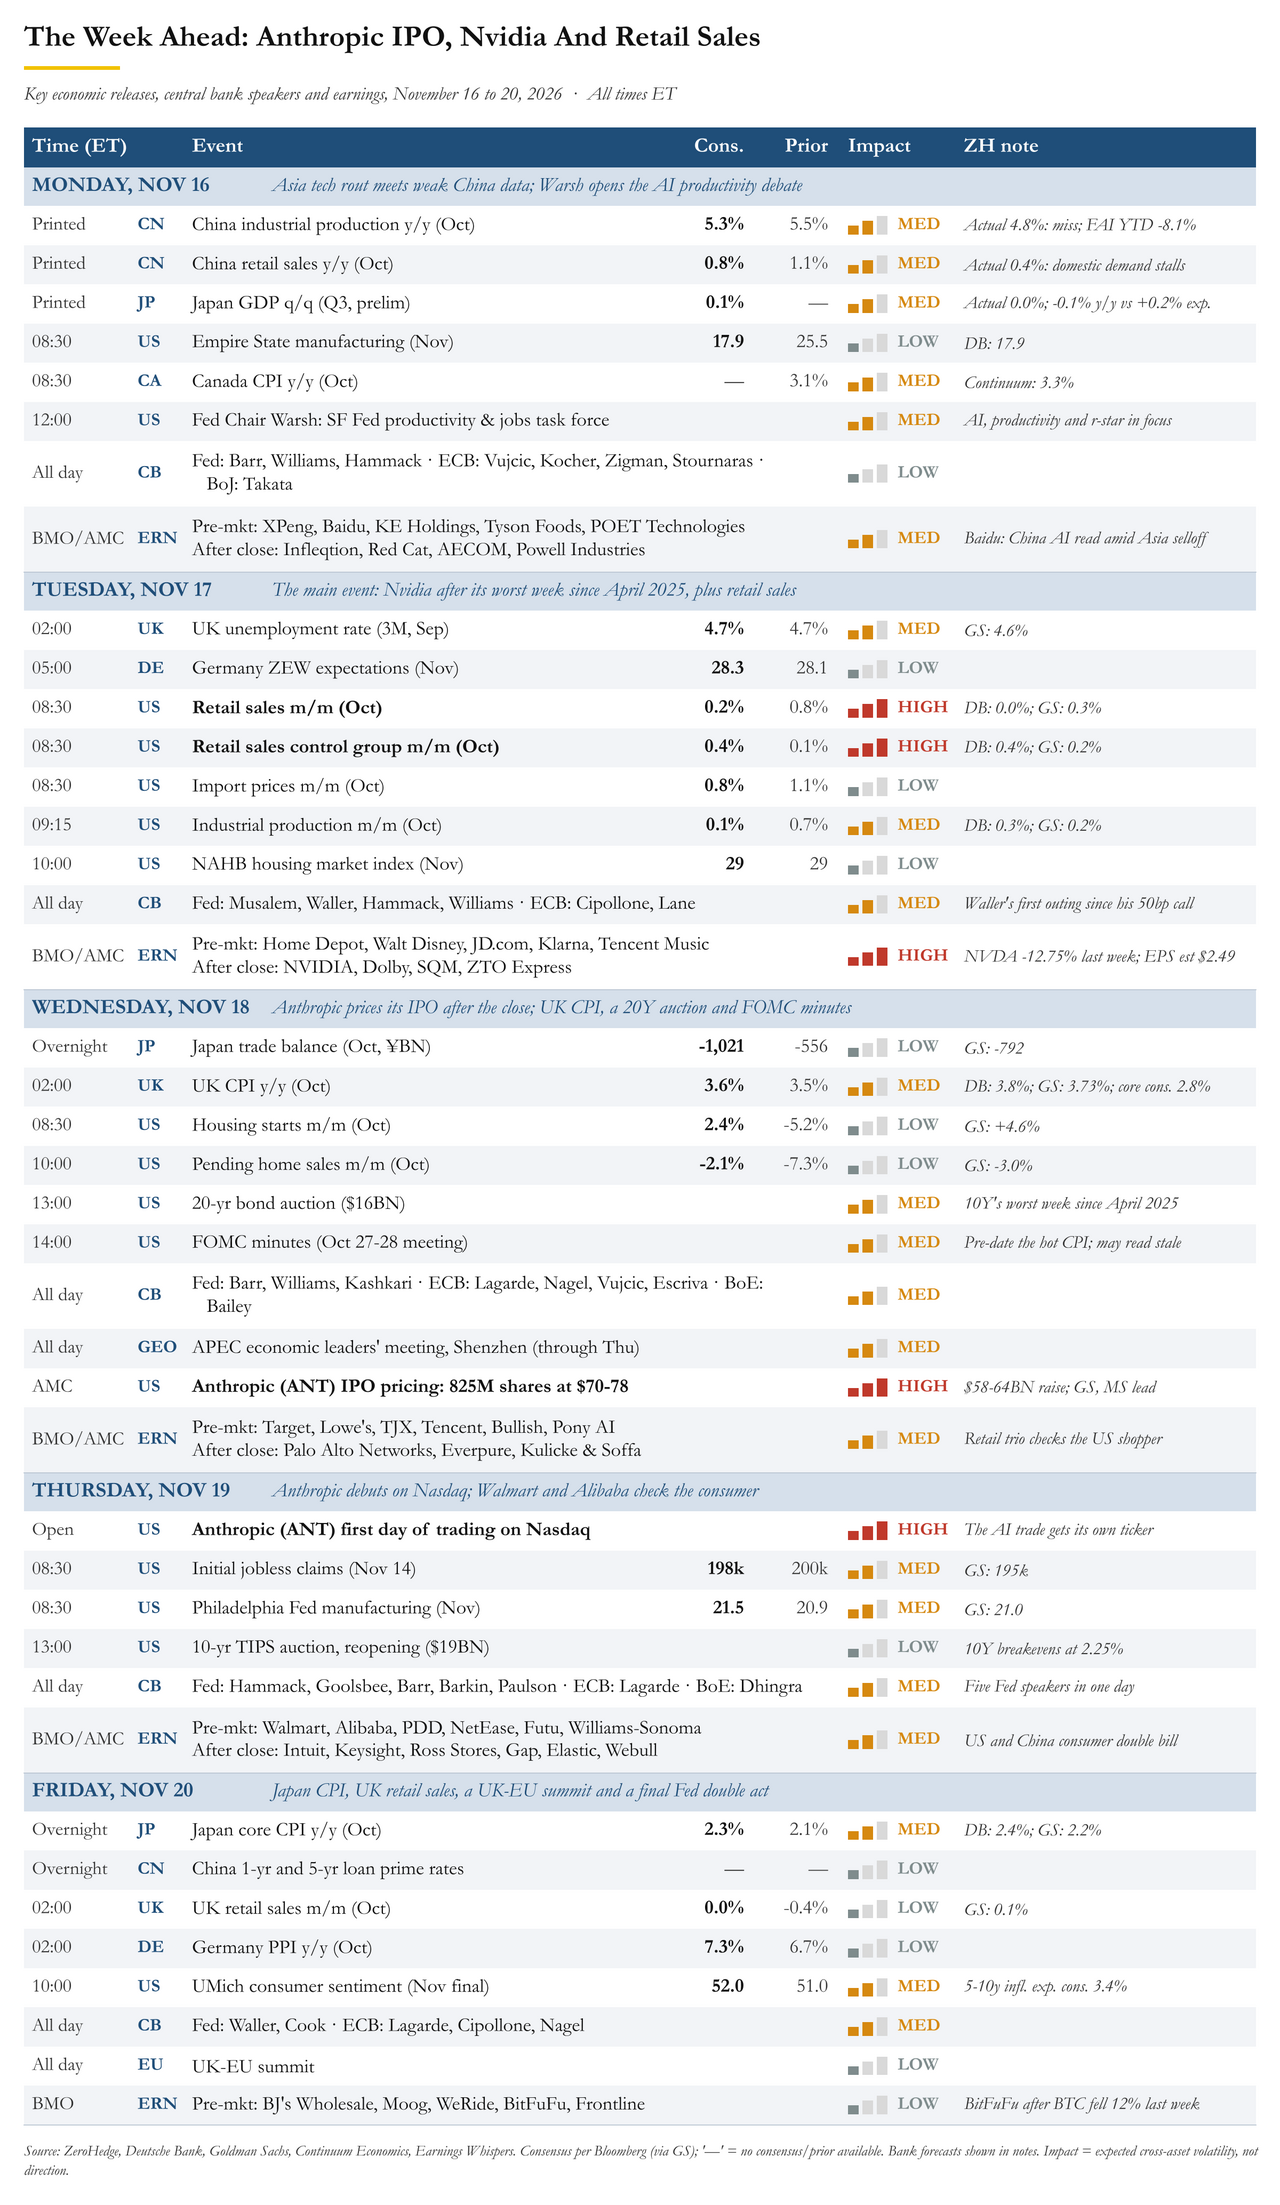
برای یک هفته پرنوسان دیگر آماده شوید. همانطور که جیم رید از DB اشاره میکند، هفته پیش رو پس از اظهارات والر و دادههای تورمی فراتر از انتظار، بازارهای زیادی را مشغول خود خواهد کرد.
Key Events This Busy Week: NVDA Eernings, Anthropic IPO, Retail Sales, US-China Summit, Fed Speakers Galore And Much More Brace for another rollercoaster week.
As DB's Jim Reid notes, the week ahead has plenty to keep markets occupied after Waller’s 50bps thunderbolt last week and the stronger-than-expected inflation data which, as we'll see at the end, led to the largest rise in US 10yr (+27.9bps) and 2yr (+33.0bps) yields since April 2025 and October 2024 respectively. Nvidia's results tomorrow may outweigh everything though and will largely put a bow on a bumper earnings season in what has been a bumpy period for markets. Tomorrow also brings US October retail sales and industrial production, Wednesday has US housing data and the minutes from the October FOMC meeting, not to mention the Anthropic IPO, while a heavy run of Fed speakers should help frame how much the inflation surprise has changed the policy debate, especially given the reaction to Waller's speech last week. Watch out for Warsh speaking today. Globally, the UK has labor-market data tomorrow and inflation on Wednesday, while Japan has Q3 GDP today and national CPI on Friday. The APEC leaders’ meeting in Shenzhen on Wednesday and Thursday adds a geopolitical angle.
Digging into the US, tomorrow’s October retail sales report should be particularly insightful after a strong +0.8% MoM increase in September. DB economists expect headline sales to be unchanged in October, with the step-down in auto sales weighing on the total. Ex-autos, DB economists expect a +0.3% MoM increase after +0.8% previously, with lower gasoline prices acting as a drag. But the underlying consumer picture should look firmer than the headline: economists expect the retail control measure to rise +0.4% MoM after just +0.1% in September. That will be an important cross-check on consumer momentum after recent data have continued to paint a picture of resilient US growth.
Tomorrow also brings October industrial production . DB's economists expect a +0.3% MoM increase, moderating from September’s strong +0.7%. So between retail sales and production, tomorrow should give us a useful snapshot of whether the economy retained momentum at the start of Q4 even as financial conditions remained relatively tight.
The backdrop to those numbers has become more hawkish after last week’s inflation data came in stronger than expected. That prompted DB's US economists to revise their Fed call: they now expect three further 25bp hikes, in December, January and March, taking the fed funds rate to 4.625% by the end of Q1 2027 . Wednesday’s October FOMC minutes therefore risk looking a little stale given they pre-date the latest inflation surprise, but they should still provide a useful benchmark for where the Committee’s policy views stood before those data. There are also almost two dozen Fed speakers this week , so markets will be looking for any evidence that the latest inflation news has shifted the broader reaction function.
Fed Chair Warsh is in focus today, moderating a panel in San Francisco as the first of the Fed’s five task forces — on productivity and jobs — presents its findings. The discussion should be particularly relevant to the current debate around AI, productivity and the labor market. DB economists’ baseline is that the task force will focus primarily on AI’s potential to lift productivity and sustain strong growth without necessarily generating the same degree of inflation pressure, although possible disruption to hiring and implications for r-star could also feature.
Housing returns to the agenda on Wednesday, with October housing starts, building permits and pending home sales all due . That will give another read on a sector that remains sensitive to elevated borrowing costs and should help fill out the picture of domestic demand alongside tomorrow’s consumer and production numbers .
Outside the US, focus will be on the APEC economic leaders’ meeting in Shenzhen on Wednesday and Thursday. In Europe, the UK has a busy week: labor-market data arrive tomorrow, followed by October CPI, RPI and PPI on Wednesday. DB's UK economists expect headline CPI to rise to +3.80% YoY from +3.48% in September and core CPI to increase to +2.87% from +2.78%. Friday then brings October retail sales and November GfK consumer confidence. Germany’s November ZEW survey is tomorrow and October PPI is on Friday, while the UK-EU summit also takes place on Friday.
Japan’s trade balance comes out on Wednesday, before October national CPI on Friday; economists expect core CPI to accelerate to +2.4% YoY from +2.1% in September, while core-core CPI is expected to slow to +2.3% YoY.
Finally, earnings season is drawing to a close but until Nvidia reports tomorrow it's hard to move on from it. Elsewhere the slower trickle of earnings sees Walmart, Home Depot, TJX, Lowe’s and Target providing a read on the US consumer. Walt Disney and Palo Alto Networks are among the other US highlights, while Alibaba, Tencent and JD.com report in China.
Data: US November Empire manufacturing index, China October retail sales, industrial production, home prices, investment, Japan Q3 GDP, September capacity utilisation, Italy September general government debt, Eurozone September industrial production, Canada October CPI
Central banks: Fed's Warsh, Barr and Williams speak, ECB's Vujcic, Kocher, Zigman and Stournaras speak, BoJ's Takata speaks
Data : US November NAHB housing market index, New York Fed services business activity, October retail sales, industrial production, capacity utilisation, import and export price indices, September business inventories, UK September average weekly earnings, unemployment rate, October jobless claims change, Germany November ZEW survey, Eurozone November ZEW survey, Canada October existing home sales, housing starts, September international securities transactions
Central banks: Fed's Musalem, Waller, Hammack and Williams speak, ECB's Cipollone and Lane speak
Data: US October housing starts, permits, pending home sales, September total net TIC flows, UK October CPI, RPI, PPI, September house price index, Japan October trade balance
Central banks: FOMC meeting minutes, Fed's Barr, Williams and Kashkari speak, ECB's Lagarde, Vujcic, Dolenc, Nagel, Escriva and Kocher speak, BoE’s Bailey speaks
Data: US November Kansas City Fed manufacturing activity, Philadelphia Fed business outlook, October leading index, initial jobless claims, Japan September core machine orders, Italy September current account balance, Eurozone September ECB current account, construction output, Q3 labour costs, Canada October industrial product price index, raw materials price index
Central banks: Fed's Hammack, Goolsbee, Barr, Barkin and Paulson speak, ECB's Lagarde speaks, BoE’s Dhingra speaks
Data : US November Kansas City Fed services activity, China 1-yr and 5-yr loan prime rates, UK November GfK consumer confidence, October retail sales, public finances, Japan October national CPI, Germany October PPI, France November business confidence, Eurozone November consumer confidence, Canada September retail sales, Denmark Q3 GDP
Central banks : Fed's Waller and Cook speak, ECB's Lagarde, Cipollone and Nagel speak
Finally, looking at the US, Goldman writes that the key economic data release this week is the retail sales report on Tuesday. There are many speaking engagements with Fed officials this week, including an event with Chairman Warsh on Monday.
05:00 AM Fed Governor Barr speaks: Fed Governor Michael Barr will speak on AI and financial stability at the ACM International Conference on AI in Finance at Bocconi University, Milan. Speech text and moderated audience Q&A are expected.
08:30 AM Empire State manufacturing survey, November (consensus 17.9, last 25.5)
09:05 AM New York Fed President Williams (FOMC voter) speaks: New York Fed President John Williams will give opening remarks at the 2026 New York Fed FX Market Structure Conference. On November 13, President Williams said that “inflation is far too high and it continues to be high even in the latest data,” adding that the Fed will “need to take actions over time that will ensure that we get inflation back to our 2% goal in a timely manner and on a sustained basis.” However, he also noted that in doing so the Fed must be “making sure that we don’t do undue harm to our maximum employment mandate.”
12:00 PM Fed Chairman Warsh speaks: Fed Chairman Kevin Warsh will give opening remarks at the Productivity and Jobs Task Force Conference held at the San Francisco Fed. Warsh will also moderate two panels and participate in a fireside chat later in the day.
02:15 PM Cleveland Fed President Hammack (FOMC voter) speaks: Cleveland Fed President Beth Hammack will appear on Bloomberg TV. On November 12, President Hammack said that “my expectations are that we need to move to a restrictive stance of policy to help bring inflation back down to that 2% objective, which is critically important.” She also noted that “the most recent data that I’ve seen show inflation is moving in the wrong direction,” suggesting that “we’re moving away from that 2% goal, rather than back down towards it.”
07:30 AM St. Louis Fed President Musalem (FOMC non-voter) speaks: St. Louis Fed President Alberto Musalem will speak at the Banco Central de la República Argentina conference in Buenos Aires on US economic scenarios and monetary policy. Speech text and moderated Q&A are expected. On October 8, President Musalem said that “to bring inflation back to target in a timely manner, more monetary policy firming will be required,” noting that “rates ought to be going up further in an appropriate period of time in the next 6-9 months.”
08:30 AM Retail sales, October (GS +0.3%, consensus +0.2%, last +0.8%); Retail sales ex-auto, October (GS +0.4%, consensus +0.4%, last +0.9%); Retail sales ex-auto & gas, October (GS +0.2%, consensus +0.3%, last +0.2%); Core retail sales, October (GS +0.2%, consensus +0.4%, last +0.1%): We estimate nominal core retail sales increased 0.2% in October (ex-autos, gasoline, and building materials; month-over-month SA) based on the signal from alternative measures of consumer spending. We estimate nominal headline retail sales increased 0.3%, reflecting higher seasonally-adjusted gasoline prices.
08:30 AM Import price index, October (consensus +0.8%, last +1.1%)
09:10 AM Fed Governor Waller speaks: Fed Governor Christopher Waller will speak on payments at the Clearing House annual conference in New York. Speech text and moderated Q&A are expected. On November 10, prior to the release of the October CPI report (which showed the core CPI increasing 0.30% month-over-month), Governor Waller said that “if the October CPI inflation data out later today are similar to the past two monthly readings—with core CPI inflation around 0.3% or even higher—then a stronger policy move may be needed. In that case, I believe a 50 basis point hike in the policy rate should be considered at the December meeting. Hiking only 25 basis points would put our credibility at risk, a risk I am not eager to take.”
09:15 AM Industrial production, October (GS +0.2%, consensus +0.1%, last +0.7%); Manufacturing production, October (GS +0.4%, consensus +0.3%, last +0.3%); Capacity utilization, October (GS 76.9%, consensus 76.8%, last 76.9%): We estimate industrial production increased by 0.2% in October, largely reflecting strong auto production. We estimate capacity utilization was unchanged at 76.9%.
09:30 AM Cleveland Fed President Hammack (FOMC voter) speaks: Cleveland Fed President Beth Hammack will give the keynote address at a Brookings Institution event on strengthening US Treasury market resilience and liquidity.
10:00 AM Business inventories, September (consensus +0.5%, last +0.4%)
10:00 AM NAHB housing market index, November (consensus 29, last 29)
02:25 PM New York Fed President Williams (FOMC voter) speaks: New York Fed President John Williams will speak in a fireside chat as part of the Axios BFD Annual Summit in New York City. Moderated Q&A is expected.
08:30 AM Housing starts, October (GS +4.6%, consensus +2.4%, last -5.2%): Housing permits, October (consensus -1.3%, last -0.4%)
10:00 AM Pending home sales, October (GS -3.0%, consensus -2.1%, last -7.3%)
02:00 PM FOMC meeting minutes, October 27-28 meeting: The FOMC left the funds rate unchanged at its October meeting, and the meeting seemed consistent with a compromise among Fed officials to hike every other meeting. Since the meeting, the inflation and labor market data have been on net firmer than expected. Following last week’s CPI report, we added a third 25bp rate hike to our forecast in March 2027, following a second 25bp hike in December. In the minutes, we will look for details on the assumptions underlying participants’ economic outlooks and views of the balance of risks at the time.
02:25 PM Fed Governor Barr speaks: Fed Governor Michael Barr will speak on community development investments at the New York Fed’s Making Missing Markets conference. Speech text is expected.
02:30 PM New York Fed President Williams (FOMC voter) speaks: New York Fed President John Williams will speak at the New York Fed’s Making Missing Markets conference.
04:15 PM Minneapolis Fed President Kashkari (FOMC voter) speaks: Minneapolis Fed President Neel Kashkari will speak at the FinRegLab AI Symposium in Washington, DC. Moderated Q&A is expected.
08:30 AM Philadelphia Fed manufacturing index, November (GS 21.0, consensus 21.5, last 20.9)
08:30 AM Initial jobless claims, week ended November 14 (GS 195k, consensus 198k, last 200k); Continuing jobless claims, week ended November 7 (consensus 1,700k, last 1,697k)
08:50 AM Cleveland Fed President Hammack (FOMC voter) speaks: Cleveland Fed President Beth Hammack will give opening remarks at the 14th annual Financial Stability Conference hosted by the Cleveland Fed and the Yale Program on Financial Stability in Cleveland.
12:30 PM Chicago Fed President Goolsbee (FOMC non-voter) speaks: Chicago Fed President Austan Goolsbee will speak at an Economic Club of Indiana luncheon event. Moderated Q&A is expected. On November 13, President Goolsbee said that “we've been above 2% for almost six years, and while sometimes we were making progress, lately we're not making any progress, and if anything, it's going the wrong way,” adding that “the central bank has definitely work to do to continue to reestablish its credibility.”
02:15 PM Fed Governor Barr speaks: Fed Governor Michael Barr will speak on AI at the FinRegLab AI Symposium in Washington, DC. Speech text and moderated Q&A are expected.
04:00 PM Richmond Fed President Barkin (FOMC non-voter) speaks: Richmond Fed President Tom Barkin will speak on the economy in a fireside chat at the Virginia Senate Finance and Appropriations Committee annual meeting in Charlottesville. Moderated Q&A is expected. On November 9, President Barkin said that “the appropriate direction of monetary policy is relatively straightforward,” but that “risks to the demand outlook remain easy to envision… and because of that, it is wise to move policy with care.”
06:30 PM Philadelphia Fed President Paulson (FOMC voter) speaks: Philadelphia Fed President Anna Paulson will speak on communications and monetary policy at a Money Marketeers of NYU event in New York City. Speech text and Q&A are expected. On November 10, President Paulson said that “further gradual tightening seems appropriate,” adding that “I prefer to tighten gradually when conditions allow it.”
08:25 AM Fed Governor Waller speaks: Fed Governor Christopher Waller will give welcoming remarks at the College Fed Challenge Finals in Washington, DC. Speech text is expected.
10:00 AM University of Michigan consumer sentiment, November final (GS 52.5, consensus 52.0, last 51.0): University of Michigan 5-10-year inflation expectations, November final (GS 3.3%, consensus 3.4%, last 3.4%)
12:15 PM Fed Governor Cook speaks: Fed Governor Lisa Cook will speak on the US economy in global context at the Central Bank of Chile’s annual conference in Santiago. Speech text and moderated Q&A are expected.
منبع: ZeroHedge — متن کامل از فید رسمی منبع، با ترجمهی ماشینی عنوان و خلاصه