صعود معاملات آتی با جهش متا بر سر جذب ۹۵ میلیارد دلاری سهام و افت قیمت نفت؛ سقوط برزیل به دنبال شوک لولا
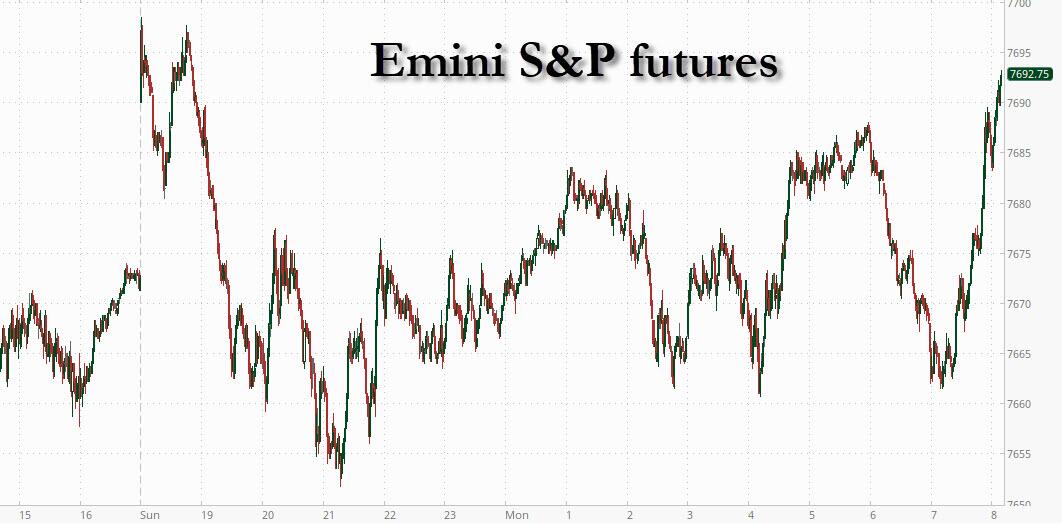
معاملات آتی ایالات متحده با امید به اینکه یک هیئت منطقهای در تهران بتواند روح تازهای به مذاکرات صلح ایالات متحده و ایران بدمد و قیمت نفت کاهش یابد، صعود کردند. همچنین جهش سهام متا پس از رونمایی از نحوه پرداخت هزینههای گزاف هوش مصنوعی، اثرات پیروزی خیرهکننده لولا در دور دوم انتخابات برزیل را که باعث سقوط ADRهای برزیلی شد، جبران کرد.
Futures Rise As Meta Jumps On $95BN Equity Raise, Oil Slides; Brazil Crashes After Lula Shock US futures are higher as oil slides on hopes that a regional delegation in Tehran can breathe some life into US-Iran peace talks, and as Meta jumps after finally unveiling how it plans to pay for its AI capex binge, offsetting a stunning comeback win by Lula in Brazil's runoff which has sent Brazilian ADRs crashing as much as 30-50% premarket, while traders brace for a week packed with megacap earnings and central bank decisions; as a result 10Y yields are flat at 4.99% and the dollar is barely changed. As of 8:15am ET, S&P futures are 0.4% higher at 7,665.75 while Nasdaq futures are up 0.7% and Dow futures rise 0.4% (+186 points) to 52,580. On Friday the S&P slipped 0.5% to cap a second weekly drop and close below its 50DMA, as the AI funding angst which has hammered tech names spread to credit. Premarket, Mag 7 names are mostly higher led by Meta (+2.4%), which is seeking up to $95 billion in equity: a $35 billion offering ($22.5 billion of Class A common stock plus $12.5 billion of mandatory convertible preferred) launched this morning, followed by an at-the-market program to sell up to $60 billion of new non-voting Class C shares starting in 2027, with Nvidia, AMD and Broadcom indicating interest in buying up to $5 billion of the offering (some circular AI financing never hurts). That the stock is rising on a potential $95 billion equity raise tells you how much the market feared the alternative was even more debt. The day's driver is Brazil: Lula's 51.8%-48.2% victory over market favorite Flávio Bolsonaro, who is now calling for the vote to be annulled, has sent the Brazil ETF (EWZ) down 27% premarket, with names like XP (-48%), StoneCo (-35%), PicPay (-34%) and Nubank (-23%) all crashing. In rates, Treasuries are narrowly mixed with the long end outperforming and the curve flattening by about 2bp, while French bonds rally after Moody's unexpectedly kept France at Aa3, narrowing the OAT-bund spread to around 158bps. The Bloomberg dollar index is up 0.1% with the yen the weakest G-10 currency, while the Brazilian real is expected to gap 5-7% lower at the open. In commodities, WTI is down about 2.1% near $101 and Brent drops toward $114 as Saudi, Turkish and Pakistani officials travel to Iran; European natgas is up 3% near a post-2022 high, while gold rises 0.5% back above $4,000 and Bitcoin hovers around $80,400. US economic data slate includes September Chicago Fed national activity index (8:30am) and October Dallas Fed manufacturing activity (10:30am); the Fed is in its blackout period ahead of Wednesday's FOMC, and the Treasury sells $69 billion in 2-year notes at 1pm.
In premarket trading, Mag 7 stocks are mostly higher: Meta Platforms (META) up +2.4% after announcing sale of up to $95 billion in common and preferred stock; Tesla (TSLA) gains 1.8% as Barclays upgrades to overweight from equal-weight, citing M&A opportunity with SpaceX; Alphabet (GOOGL) +0.5%, Amazon (AMZN) +0.2%, Microsoft (MSFT) +0.4%, Nvidia (NVDA) +0.4%, Apple (AAPL) -1.7%. Here are some of the other notable premarket movers:
US-listed shares of Brazilian companies, and those exposed to the country, slump after President Luiz Inácio Lula da Silva surprised the markets to come from behind to win a runoff election. Among movers: PagSeguro (PAGS) -32%, NU Holdings (NU) -25%, MercadoLibre (MELI) -14%
ArriVent Biopharma (AVBP) is trading higher by 4.5% after early-stage data for the company’s ARR-217 product candidate was presented at ESMO, a key cancer conference.
Booz Allen Hamilton Holding Corp. (BAH) rises 0.9% as it is being upgraded to buy from hold at TD Cowen, which writes that shares of the IT services company look attractively valued in the wake of long-term share-price weakness.
Borr Drilling shares (BORR) drop 8.2% after the company said search and rescue operations are ongoing for five individuals who remain unaccounted for after its Prospector 5 drilling rig sank during jacking operations offshore Gabon on Oct. 24.
Coinbase Global Inc. shares (COIN) are down 1.7% as Bernstein cut its price target on the exchange to $250 from $330 on lower expected crypto volumes.
Equifax Inc. (EFX) falls 3.5% after it was cut to sector perform from outperform with RBC saying the the recent stock rally “off the lows has left risk/reward more balanced” given concerns on higher rates, regulatory overhand and consumer lending pressure.
Fair Isaac Corp. (FICO) falls 9.2% after it was cut to equal-weight from overweight at Wells Fargo, citing its lower-than-expected 2027 pricing announcement.
FirstEnergy Corp. shares (FE) rise 0.5% after BMO Capital Markets initiated coverage of the utilities company with a recommendation of outperform as it sees an attractive valuation.
Lockheed Martin Corp. shares (LMT) are up 1.4% after Morgan Stanley upgraded the defense company to overweight from equal-weight, writing that a recent deal for F-35 fighter jets “takes significant risk out of the stock.”
Moderna (MRNA) slumps 8.2%, set to extend their decline for a third session, after the drugmaker gave results from a trial of its experimental vaccine used in the treatment of pancreatic cancer.
Nutanix Inc. shares (NTNX) are up 5.3% after Guggenheim Securities started coverage on the infrastructure software company with a buy rating and $100 price target, seeing an ability for it to take market share.
Range Resources (RRC) rises 8.9% after EQT (EQT -8.1%) agreed to buy the energy firm in an all-stock transaction to create a combined natural gas company with a pro forma enterprise value over $50 billion.
Spotify Technology SA shares (SPOT) are down 1.4% after Phillip Securities downgraded the audio-streaming company to accumulate from buy, a move that comes in the wake of its recent results.
Xencor (XNCR) climbs 31% after the drug developer gave updated results from an early-stage trial of its experimental drug for kidney cancer that impressed Wall Street.
In other corporate news, Meta, whose 5-year CDS has roughly doubled since August to about 120bps as its capex is now seen exceeding operating cash flow, decided that if the bond market is getting nervous, shareholders can foot the bill: the company launched a roughly $35 billion offering of $22.5 billion in Class A common stock (sold via forward sale agreements) and $12.5 billion in three-year mandatory convertible preferred stock, and plans an at-the-market program of up to $60 billion of new non-voting Class C shares once they start trading, expected in Q1 2027, for a total of up to $95 billion; Nvidia, AMD and Broadcom indicated nonbinding interest in buying up to $5 billion of the shares, which are being sold to fund AI infrastructure and compute capacity. EQT agreed to buy Range Resources in an all-stock transaction, with each Range share exchanged for 0.987 EQT shares, creating a gas giant with a combined enterprise value of more than $50 billion; RRC is up 14% premarket while EQT drops 4.2%. Verizon raised its full-year adjusted EPS forecast to $5.04 to $5.06 from $4.99 to $5.04 after posting its biggest third-quarter wireless-customer additions in five years. Instacart is in talks to sell itself, the Information reported. Amex plans to cut 5% of its headcount as transaction volumes fall short. Ovintiv agreed to buy Canada's Logan Energy in a Montney expansion. Elon Musk said SpaceX closed a $40 billion debt deal to fund chips for its AI ambitions, although people familiar said pricing talks were still underway. Challenger's board rejected a $4.4 billion offer from Daiichi Life.
Global markets are trying to start the week on a positive note as crude retreats from a six-month high, but it's a deceptively calm surface: a shock win for Luiz Inácio Lula da Silva in Brazil's election will dominate today's narrative , while the AI trade will be tested this week when tech firms worth more than $10 trillion combined, including Microsoft, Amazon and Alphabet, report earnings. As Bloomberg's Before the Bell notes, the Nasdaq is at a key technical level after a second week in the red, hovering around 29,000 after a failed breakout sent it back toward the lower end of its six-month range; a loss of recent lows would expose the 200-DMA near 27,800, about 3.5% below current levels .
The bigger issue is how all this AI capex gets paid for. Meta's raised capex guidance alarmed some, as consensus is now modeling about $140 billion in spending, pushing that metric above operating cash flow , and the concerns are spilling into credit, with Meta's five-year CDS spread roughly doubling since August to around 120 basis points, confirming what we warned last week when Goldman admitted its credit bear case isn't bearish enough as AI stress hits bonds . Today we got the answer to the funding question: Meta is seeking up to $95 billion in equity to fund its AI spending , after last week's results showed it raised the low end of its 2026 capex guidance, turned free-cash-flow negative and flagged multi-year equity funding needs through new Class C shares (per Goldman's TMT desk). The stock fell 7% on Thursday when the issuance plans overshadowed a revenue beat, but is up 2.4% premarket now that the size of the overhang is known and the chipmakers it pays for GPUs have offered to buy some of the paper back. Meanwhile, the stress at the bottom of the credit stack is getting worse: average yields on triple-C rated junk bonds topped 16% for the first time since 2020 on Friday , and last week's 1.6% loss was the biggest in 18 months.
Elon Musk's weekend comments didn't help: he said debt markets have "almost entirely shut off access to money" for companies without substantial revenue outside AI data centers , adding that "200+ neoclouds are going to see guppy-level death and consolidation," which is why CoreWeave (-5.5%) and Nebius (-4%) are sliding premarket even as the broader market rises. Morgan Stanley's Mike Wilson, meanwhile, sees AI-related concerns as one of three clearing events that could help end the market correction over the next few weeks, and reckons quality can hold up even if the S&P trades toward his tactical downside zone of 7,100-7,200.
“For today, however, expect Brazilian markets to be hit hard. USD/BRL gapping 5-7% higher at the open to the 5.20/25 area should be no surprise, while the local Bovespa equity index looks set for double-digit losses,” said Chris Turner, ING's head of FX strategy. “Important for local financial markets will be how quickly Bolsonaro accepts the result – or at least allows the constitution to run its course.”
“As such, BRL is poised to unwind its rally following Bolsonaro’s strong first-round showing earlier this month,” said Elias Haddad, global head for markets strategy at Brown Brothers Harriman. “Lula’s greater tolerance for rising debt adds to BRL headwinds.”
Elsewhere, HSBC's long-standing equity bull Max Kettner is dialing back risk , moving to neutral on equities from maximum overweight and to overweight developed-market government bonds from maximum underweight, saying bond underperformance "has become stretched" and that "constant narrative bingo" means the team no longer has the same level of conviction; HSBC also cut its gold overweight and raised oil to outright overweight.
JPMorgan's Market Intel desk (Andrew Tyler) remains "Tactically Bullish" , noting the SPX has lost 2.4% over the last two weeks with a shift toward defensives, and that "we have yet to have a complete positioning washout despite sentiment being firmly in the Fear region." On Iran, "If Trump moves back to negotiations rather than kinetics, then we expect a broad-based rally led by Tech / Cyclicals ex-Energy." As for Brazil, JPM's prior Monetization Menu noted that "internationally, we continue to favor Brazil and Japan" (it was a good run while it lasted). JPM's Mike Feroli expects a hold on Wednesday with two hawkish dissents (Hammack and Logan), and says Chair Warsh will have to explain why the committee hiked after a two-tenths core PCE print in September but is now holding after an expected three-tenths outturn .
Over at Goldman, Rich Privorotsky summed up the mood: "Positioning, sentiment and performance all severely constrained…. shorts squeezing, nothing working. Usually darkest before the dawn." According to the bank's Giulio Esposito, Global Tech is "registering its largest 2-week net selling on record" , fundamental L/S net leverage has dropped to a one-year low of 47%, while Mag 7 net exposure is at a record high, which echoes what we noted over the weekend in "The AI Hangover: Goldman Says Buy The Dip As Hedge Fund Stop-Outs Push Nets To A One-Year Low" . Goldman's Brian Garrett frames the dilemma: "we're either in the 2nd inning of a repricing of the entire AI ecosystem … or we're in the 8th inning of a significant de-gross episode (leaning in this camp right now)" . Also of note, GS calculates that CTAs are long $38.5 billion of S&P futures (91st percentile) and could sell $11.6 billion over the next week even in a flat tape. Goldman economists expect the FOMC to skip on Wednesday but deliver a second and final hike in December.
Positioning may yet provide a cushion: Deutsche Bank strategists note tech exposure has slid to the lowest level in six months and is now close to Iran war lows, even as investors poured about $30 billion into tech funds over the past two weeks, including $12 billion into leveraged ETFs; that dip-buying showed signs of cracking last Thursday, when the selloff triggered about $1.5 billion of outflows .
In geopolitics, Trump said it's "getting to be decision time" on whether he will make a deal with Tehran or resume attacks , as Iranian and Houthi threats against Americans in the Middle East continue to grow; meanwhile, Kevin Hassett said US-Canada trade negotiations are "gathering steam." In France, the government avoided a repeat of the looting of the prior weekend, and Moody's surprise decision to hold France's rating has given OATs a stay of execution (S&P is up next on Nov. 27); for more on where French and European spreads go from here, see Goldman's latest warning on Europe's election cycle .
In Europe, the Stoxx 600 rises 0.4% to 638.10 with 442 members up and 141 down, as cyclicals lead and defensives lag, a reversal of recent performance, ahead of a busy earnings week. France's CAC 40 outperforms with a 0.9% gain after Moody's held the nation's rating, and the DAX rises 0.9% after the Ifo business climate index unexpectedly improved for a sixth month to 90.2, while Spain's IBEX is the laggard as Telefonica slumps 7% on a JPMorgan downgrade and Santander falls 4% on its Brazil exposure. Travel & leisure and autos lead, while energy trails as crude retreats. JPM's desk notes the top baskets are Freight Sensitives, MidEast Escalation Shorts and Power, while Diesel plays, Oil sensitives and MidEast Escalation Longs are lower, and Growth/Momentum lead. Here are the biggest European movers:
Genmab shares surge as much as 13%, the most since March 2020, after the drugmaker said a late-stage trial of its experimental treatment for ovarian cancer, Rina-S, met its primary and key secondary endpoints. The company separately gave a positive update for petosemtamab, a drug being developed to treat colorectal as well as head and neck cancer.
Roche shares gain as much as 1.9%, to the highest since April 2022, after the pharma producer’s experimental lung cancer drug, divarasib, fared better than rivals in a late-stage study.
PostNL shares gain as much as 5.4%, the most since Aug. 3. The Dutch courier service upgraded its free cash flow outlook to the upper end of the range and reiterated its full-year Ebit guidance, which analysts received positively in spite of weaker-than-expected volume growth in the third quarter.
Plus500 shares rise as much as 4.6%, the most since Sept. 30, after the trading platform said it expects its financial performance to be ahead of current market expectations for FY26.
Man Group shares gain as much as 4.9%, the most since Sept. 17, after Meiji Yasuda Life Insurance says it plans to acquire a 5% stake in the UK asset manager.
European stocks with exposure to Brazil fall after President Luiz Inacio Lula da Silva came from behind to win the country’s runoff election, putting fiscal policy in focus and raising concerns that Brazilian interest rates could remain higher for longer. Among decliners are telecom operator Telefonica, lender Santander, online casino supplier Evolution
GTT shares drop as much as 15%, the biggest decline since 2020, after the engineering firm reported a decline in revenue over the first nine months of the year.
BASF shares fall as much as 1.8% after a downgrade to hold from buy at Deutsche Bank. Uncertainty over the potential acquisition of Evonik is likely to create a “material overhang” over the stock, according to the bank’s analysts.
Asian stocks were mixed with a mostly negative bias, as weakness in technology shares in Korea and Japan persisted ahead of a slew of tech earnings. The MSCI Asia Pacific Index slipped as much as 0.2%, with Samsung Electronics among the heaviest drags. Korea's Kospi fell 1.3% (foreigners were the only net sellers), while SK Hynix bucked the broad AI selloff on the prospect of a hefty special dividend tied to its Kioxia stake. Japan's Nikkei 225 dropped 0.8%, with Advantest's 3.9% slide accounting for about 55% of the decline according to Goldman, while miners and oil names rallied. Hong Kong's Hang Seng bucked the trend, rising 0.5% led by energy names such as PetroChina (+5.8%), even as mainland investors sold for a ninth straight session via Stock Connect. China's CSI 300 was flat (-0.04%) as China's fifth plenum got underway, Australia's ASX 200 edged up 0.2%, Indonesia's JCI fell 1.5%, and Taiwan was closed for a holiday.
In FX, the Bloomberg Dollar Spot Index is up 0.1% and the yen is the weakest G-10 currency, with USD/JPY up 0.3% near 157.30 ahead of Friday's BOJ decision. The euro holds just above 1.12 after France avoided a Moody's downgrade, while the pound lags ahead of Wednesday's UK budget. The Brazilian real is expected to gap sharply lower at the open, with ING seeing USD/BRL up 5-7% to the 5.20/25 area and Goldman's desk flagging a 10% move. Elsewhere, asset managers' short positions on the Aussie dollar surged to a record high in the week ended Oct. 20.
In rates, Treasuries are narrowly mixed with the long end outperforming, flattening the yield curve as investors set up for front-loaded auctions on Monday and Tuesday ahead of Wednesday's FOMC decision. Front-end yields are slightly cheaper on the day, with the 2-year up 1bp at 4.69%, while the 30-year is lower by around 1bp, flattening 2s10s and 5s30s by about 2bp; the 10-year is little changed near 4.98%. This week's auctions begin with $69 billion 2-year notes at 1pm ET, followed by $70 billion 5-year notes Tuesday and $44 billion 7-year notes Thursday; the WI 2-year yield near 4.69% is about 10bp richer than last month's auction, which tailed by 0.2bp . Traders are pricing just a 13% chance of a hike on Wednesday while largely pricing in a 25bp hike in December (so much for a dovish Fed under Warsh). In Europe, French bonds outperform after Moody's maintained France at Aa3 with a negative outlook, defying expectations of a downgrade , taking the OAT-bund spread to around 158bps from Friday's 176bps peak, while bunds slip as gas prices jump and the unwind of haven flows sends money back into French debt. IG dealers expect around $30 billion of issuance this week as companies emerge from earnings blackouts.
“Risks to Treasury yields skew modestly higher over the near term, especially given that 10-year yields are once again flagging 15bp too low in our fair-value framework,” said JPMorgan's Jay Barry.
In commodities, oil is lower with WTI down about 2.1% around $101 and Brent trading near $114, as senior officials from Saudi Arabia, Turkey and Pakistan meet Iranian counterparts in Tehran and Iran's foreign minister proposed a 7-day plan to reopen the Strait of Hormuz, subject to conditions. Supply risks haven't gone anywhere: UKMTO reported a tanker transiting Hormuz was struck by a projectile on Oct. 23, the Houthis claim to have targeted Saudi Arabia's East-West crude pumping stations, crude in floating storage rose 8% in the past week according to Vortexa, and IEA chief Birol says he sees no credible pathway for energy markets to return to pre-Iran war levels in 2027. Dutch TTF gas bucks the trend, up about 3% toward €97/MWh and near the €100 mark on colder weather forecasts. Spot gold is back above $4,000/oz, up 0.5% around $4,016, silver trades around $54, and LME copper is little changed.
US economic data slate includes September Chicago Fed national activity index (8:30am) and October Dallas Fed manufacturing activity (10:30am). The Fed is in its external communications blackout ahead of Wednesday's decision. Earnings before the open include Verizon; after the close, Cadence Design, Amkor, Rambus, Welltower, Whirlpool, Brown & Brown and Alexandria Real Estate report.
Lula da Silva won a record fourth term as Brazil’s president in a surprise runoff defeat for Flávio Bolsonaro, who said he’ll challenge the result. Local markets are bracing for a rout, with a New York ETF tracking Brazilian equities sinking 27% premarket. BBG
ING says the Brazilian real can slide 5-7% at the open on Lula's victory, with the Bovespa set for double-digit losses; Brazil's B3 changed trading range limits for rates, FX and the Bovespa. BBG
Meta is seeking up to $95 billion in equity to fund AI spending: a $35 billion offering of $22.5 billion in Class A common stock and $12.5 billion in mandatory convertible preferred, plus an at-the-market program for up to $60 billion of non-voting Class C stock expected to start in Q1 2027; Nvidia, AMD and Broadcom are interested in buying up to $5 billion of Meta stock. Shares rise 2.4% premarket. BBG
Saudi, Pakistani, and Turkish defense officials will travel to Tehran on Monday to discuss the region’s security challenges. Al Jazeera
US forces in the Middle East are prepared to launch new, potentially major, military operations against Iran “within 96 hours of receiving” an order from President Donald Trump, according to two US officials. CNN
UKMTO received a time-late report that a tanker transiting the Strait of Hormuz was struck by an unknown projectile on Oct. 23, disabling the vessel. BBG
No end is in sight to a $3.5 trillion selloff in Chinese stocks as investors see little urgency from leaders to jump-start the economy. BBG
The EU plans safeguards to cut imports from Chinese sectors including chemicals, furniture and machinery, people familiar said. The measures may be unveiled as soon as the first quarter. BBG
The Dutch government aims to cut 25,000 civil servant jobs in an AI-led efficiency drive targeting annual savings of €3.5 billion. BBG
President Donald Trump at a Sunday political rally predicted a trade dispute with Canada would be resolved "soon," without providing specifics. RTRS
French assets rallied after the country avoided a Moody’s downgrade and a repeat over the weekend of large-scale violence and looting. BBG
Trump pledged more announcements on the economy after Volkswagen unveiled plans to build a new $4 billion Audi factory in Georgia. The president’s failure to bring down the cost of living is weighing on Republicans’ midterm campaigns. BBG
EQT agreed to buy Range Resources in an all-stock transaction, with each Range share exchanged for 0.987 EQT shares; the combined company will have an enterprise value of more than $50 billion. RRC rises 14% premarket, EQT falls 4.2%. BBG
Average yields on triple-C rated junk bonds topped 16% for the first time since 2020 on Friday, and last week’s 1.6% loss was the biggest in 18 months. BBG
HSBC strategists moved to overweight developed-market government bonds from maximum underweight, saying underperformance “has become stretched,” and turned neutral on equities from maximum overweight. BBG
Germany's Ifo business climate index rose to 90.2 in October, beating the 89.9 estimate and improving for a sixth month. BBG
The PBOC unveiled a liquidity backstop for non-bank bond investors, setting up a swap facility for large non-bank bond redemptions. BBG
Elon Musk said SpaceX has closed a $40 billion debt deal to pay for the chips needed to fuel its AI ambitions; people familiar said pricing talks were still ongoing. BBG
Instacart is in talks to sell itself, citing people familiar with the matter: The Information
Amex is set to slash 5% of headcount as transaction volumes fall short. BBG
US President Trump posted "...Libya cannot remain a corridor for illegal migration, and this must end now. The United States remains firmly committed to strengthening our bilateral relationship". Truth Social
Goldman expects the FOMC to skip raising rates at its October meeting but to deliver a second hike in December; JPM's Feroli sees a hold with two hawkish dissents (Hammack and Logan). GIR / JPM
A more detailed look at global markets courtesy of Newsquawk
APAC stocks were mixed with a mostly negative bias following last week's surge in oil and amid ongoing geopolitical risks, while participants await this week's tech earnings and several major central bank rate decisions. ASX 200 mildly outperformed, with the index kept afloat as strength in the local real estate, tech and the commodity-related sectors offset the losses in defensives, telecoms and financials. Nikkei 225 was lower amid tech headwinds and with SoftBank choppy after reports that its CEO Son is discussing a USD 50bln investment plan in Malaysia focused on AI and data centres. KOSPI retreated with some indecision seen in the tech heavyweights ahead of their Q3 earnings results this week, while SK Hynix clarified it is considering various shareholder‑return options, but added that nothing was decided and it will unveil additional plans after its Q3 earnings announcement, in response to reports that it plans a KRW 16.0tln special dividend from gains on its Kioxia investment. Hang Seng and Shanghai Comp were mixed with price action range-bound amid several earnings releases, while trade frictions lingered with China firmly opposing a US Treasury proposal to expand the scope and severity of restrictions on US investment in China.
Japan's Top Automobile Industry Union Group Chief said "we look beyond inflation-linked pay hikes for 2027 labour talks".
China's fifth plenum gets underway, as scheduled, which is a closed-door convention involving officials from the Communist Party's Central Committee, while President Xi delivers the Work Report at the plenum, according to CCTV.
Japanese PM Takaichi said she wants results on tax cut and oil diversification bills.
European bourses (Stoxx 600 +0.4%) are broadly firmer this morning, following on from a mixed APAC handover. The CAC 40 (+0.9%) is amongst the outperformers, after Moody’s maintained France's credit rating at Aa3 with a Negative Outlook despite recent civil unrest and rising political risks. A decision which comes despite the heightened risk of a downgrade, and hence lifted French-related assets. Over in Spain, the IBEX 35 (-0.5%) is the European underperformer, weighed on by pressure in Telefonica (-7%). The Co. was subject to a downgrade at JPMorgan (Neutral to Underweight), with the firm citing concerns related to its debt structure and its UK JV, VMO2. Moreover, Santander (-4%) shares have fallen following Brazil President Lula's victory in the elections, with investors now worried about the fiscal situation in the region. European sectors hold a strong positive bias. The typical cyclical sectors hold towards the top of the pile, with Travel & Leisure leading, joined closely by Autos. A move facilitated by pressure in the crude complex, which in turn has pushed the Energy sector towards the foot of the pile. There has been a lot of focus on some healthcare names this morning; AstraZeneca (+1%, SAFFRON Phase III trial showed statistically significant improvement in progression-free survival vs chemotherapy), Bayer (+3.3%, Phase III DASL-HiCaP trial showed a statistically significant 58% reduction in the risk of metastasis vs the placebo), Novartis (-0.3%, Remibrutinib met its primary endpoint but fell short of analyst expectations). Other key movers: Man Group (+4.7%, Co. expands partnership with Meiji Yasuda), Computacenter (+8%, lifts profit forecast), Plus500 (+4%, raises FY26 outlook after reporting solid Q3 growth). US equity futures (ES +0.4%, NQ +0.4%, RTY +0.4%) are all trading with modest gains this morning. The complex has been gradually moving higher in early trade, benefiting from the pressure seen in oil prices throughout the morning. There was no real driver for the action, but with markets potentially focusing on a delegation meeting (including Saudi Arabia, Turkey and Pakistan) in Tehran on Monday.
UK Chancellor Healey will use his budget this week to protect pensioners and those saving for their retirement as he announces plans to shield nearly one million people from paying income tax, according to The Times. Healey is expected to confirm on Wednesday that the full state pension will rise by GBP 489 to GBP 13,036, and that will be equivalent to a 3.9% rise.
UK Chancellor Healey will use the upcoming budget to give mayors in England additional funding and powers, including a GBP 1.5bln borrowing facility, as part of plans to shift economic decision-making away from Westminster.
UK pledged GBP 100mln for an AI Biosecurity Lab supported by OpenAI, Anthropic and Google DeepMind, as part of efforts to improve the government's ability to understand and address risks posed by the technology.
UK PM Burnham said he is "not proposing re-joining the EU in this parliament", Sky's McDaid reported; but would like to re-join at some point in his lifetime.
UK PM Burnham rules out an early election; said, "I don’t think people want another backward looking squabble. They want me to get on with the job", The Times reported.
UK PM Burnham opened the door to Britain readopting the EU's free-movement rules, according to The Sunday Times. It was separately reported that Burnham called for an 'honest discussion' on the free movement of people, which has sparked a furious debate over Britain readopting EU free movement rules, but rejected the idea that the UK could join the euro or the passport-free Schengen travel area, according to FT.
UK PM's office said the UK is to spend an additional GBP 432mln to help curb homelessness.
Protests against the war and rising living costs took place in major Italian cities on Saturday, with some incidents of violence following recent unrest across the country.
France avoided a repeat of large-scale violence and looting during Saturday's protests, which involved around 110K people in a largely peaceful demonstration confined to the outskirts of Paris and another 300K nationwide. The CGT union put the total at 800K. However, isolated clashes were reported in several cities, with police using tear gas and water cannons.
France's National Rally reelected Bardella as party president in Orléans on Saturday with 98.98% of the vote, with no opposing candidate, while National Rally's Le Pen vowed a national ‘renewal’ in a campaign launch.
Moody's maintained France's credit rating at Aa3 with a Negative Outlook despite recent civil unrest and rising political risks, while Scope reaffirmed Italy's rating at BBB+ with a Positive Outlook.
G10s are broadly softer against a firmer USD. The JPY underperforms, joined closely by the GBP. The EUR holds up relatively well, after France avoided a ratings downgrade from Moody's on Friday.
DXY softened in Asia as oil prices pulled back and yields eased, but has gradually ground higher since, and currently sits at the top end of a 101.58 to 101.82 range ahead of Friday and Thursday’s peaks at 101.85 and 101.88 respectively. The US data docket is light for the day (Dallas Fed Manufacturing, Chicago Fed National Activity), so attention turns to Wednesday's FOMC, where money markets lean heavily towards a hold, alongside a busy week of tech earnings and any US-Iran developments. In geopolitics, President Trump said he is nearing a decision on whether to strike a deal with Iran or resume military strikes. Meanwhile, Barclays' month-end model points to weak USD buying vs most majors, with no directional bias against EUR or JPY.
GBP was the initial laggard this morning, but now off worst levels and remains towards the bottom of the G10 pile. Cable trades at the bottom end of a 1.3344-1.3388 range after finding resistance at the 100 DMA (1.3387), with no clear driver for the weakness apart from a myriad of UK budget leaks over the weekend and relative aforementioned EUR resilience. Focus this week is on Wednesday's Autumn Budget, where Chancellor Healey is expected to confirm a 3.9% rise in the full state pension, while it was also reported over the weekend that PM Burnham opened the door to Britain readopting the EU's free-movement rules.
EUR/USD trades in a tight 1.1202-1.1227 range, holding just above the 1.12 mark, where EUR 1.2bln of options roll off at today's NY cut. Moody's maintained France's Aa3 rating with a negative outlook on Friday, defying some expectations of a downgrade, while France largely avoided a repeat of the looting seen during previous protests on Saturday; further protests are planned for 31st October and 5th November. The ECB policy decision is due on Thursday.
USD/JPY is firmer and holds towards the upper end of a 156.65-157.34 range, with USD 3.1bln of options at 158.00 rolling off at today's NY cut. The BoJ is widely expected to keep rates on hold when it concludes its two-day meeting on Friday.
The Antipodeans are softer; NZD/USD trades towards the bottom end of a 0.5685-0.5707 range, while AUD/USD holds within a 0.7022-0.7040 band. Both are in focus this week, with the RBNZ policy decision on Wednesday and Australian CPI also due Wednesday.
CFTC Positioning (w/e 20th Oct): USD net long; EUR net short; JPY net long; GBP net short; AUD net short; NZD net short; CAD net short; CHF net short.
Brazil's Electoral Authority confirmed that Brazil's Lula was re-elected president in the runoff vote, while Bolsonaro said extending voting hours was unacceptable, and it is impossible to acknowledge election results. Furthermore, Bolsonaro said they will ask that the election be annulled.
PBoC set USD/CNY midpoint at 6.7162 vs exp. 6.6691 (prev. 6.7180).
RBA's Brad Jones said in panel participation at AFR Super and Wealth Summit that super tailwinds will become headwinds as members deaccumulate and that unexpected super early release poses financial stability risk. AI valuations are punchy with increasing debt and vendor financing. Geopolitical fragmentation poses new financial system risks.
PBoC is to set up bond market NBFI swap facility to maintain bond market stability.
Swiss Weekly Sight Deposits (w/e Oct 23) Total: 434.743bln (prev. 457.01bln); Domestic 434.743bln (prev. 435.36bln).
A slightly mixed start to the week for fixed income. Initial strength was a function of the energy pullback; however, benchmarks remain at elevated levels given the punchy rhetoric, and Dutch TTF has climbed significantly this morning, bringing the EUR 100/MWh mark into view.
USTs were firmer by around five ticks early doors, at a 106-10+ peak, shy of last week’s highs at 106-14+ and 106-16+ from Friday and Thursday respectively. This week is, of course, dominated by the Fed on Wednesday. Ahead of that, geopolitics will continue to influence, and by extension the recent growth/inflation discourse will feature, before PCE post-Fed.
OATs opened higher by around 70 ticks, after Moody’s maintained the rating, an Aa3, Outlook Negative rating that is one notch higher than both S&P and Fitch’s assessment of France. The hold was broadly on the assumption that a deficit-reducing budget will at some point be adopted. Given the challenging political and deteriorating fiscal backdrop in France, this was perhaps a stay of execution rather than a change in the narrative; next, we have S&P on November 27th.
Upside that has largely held for OATs, and by extension the OAT-Bund 10yr yield spread has narrowed by almost 8bps today, after narrowing a similar amount on Friday, taking it to a 158bps low, vs Friday’s 176bps recent peak. However, MTD, it remains wider by over 30bps.
Bunds in-fitting with USTs directionally, saw a slightly larger pullback in early hours and is hit by around 30 ticks at the time of writing, a function of the mentioned gas strength and as we look to this week’s ECB, with Moody’s hold on France removing one of the arguments for a, relatively speaking, more-dovish confab. Currently, at a 121.87 low.
Finally, Gilts opened with very modest gains, before succumbing to the regional pressure and slipping by around 10 ticks. However, Gilt action is comparably a touch more contained, as focus remains firmly on the budget, while weekend press updates on that and UK PM Burnham's approach to the EU were unsurprising, but still a net-supportive factor for the benchmark.
Schneider Electric (SU FP) to sell EUR-denominated notes in a six parter.
Crude benchmarks are lower by over 1.5% this morning, extending on the pullback seen in the Asia-Pac session. WTI Dec'26 currently holds at the bottom end of a USD 100.60-102.63/bbl range, whilst Brent Jan'27 trades at the lower end of a USD 109.22-110.98/bbl band. However, both benchmarks remain comfortably within Friday's broad ranges (WTI: USD 98.84-103.92/bbl; Brent: USD 108.33-112.45/bbl), when crude surged and both benchmarks closed near the top of their ranges.
The gradual pressure in the crude complex lacks a clear driver, but markets may be focusing on a meeting in Tehran on Monday between senior officials from Saudi Arabia, Turkey and Pakistan and their Iranian counterparts, to discuss regional coordination. On the diplomatic front, Iran's FM Araghchi proposed a 7-day plan to reopen the Strait of Hormuz, subject to conditions, while US President Trump said he is nearing a decision on whether to negotiate a deal with Iran or resume military strikes. The pullback in crude has helped lift broader sentiment across equities this morning.
Dutch TTF bucks the trend and is firmer by c. 3%, holding towards the upper end of a EUR 94.25-97.64/MWh range. The contract has climbed steadily throughout the Asia-Pac session and into the European morning, although it has eased slightly from its session peak. There has been no clear headline catalyst for the move, although colder weather forecasts have been cited as supportive, while the European gas benchmark remains underpinned by ongoing LNG disruptions and low EU storage levels heading into the winter period. Elsewhere, Iran's President is set to visit Russia today to attend the gas exporting countries' summit, while Goldman Sachs last week said it still sees upside risks to its year-end TTF forecast of EUR 70/MWh. Across the Atlantic, Henry Hub futures are a touch lower, within a USD 2.932-3.026/MMBtu range.
Precious metals are firmer, with spot gold back above the USD 4k/oz mark and holding at the upper end of a USD 3,978-4,022/oz range, after trading sideways just beneath that level overnight, as participants await this week's central bank announcements, including the FOMC on Wednesday. Spot silver trades within a USD 53.62-54.41/oz band.
3M LME Copper is little changed and sits at the top end of a USD 14,247.78-14,361.18/t range.
US CENTCOM said it helped Gulf states export more than 1.5bln bbls of oil since the summer.
Libya reopened the oil pipeline from the Hamada and Tahara oilfields to Zawiya. It was also reported that
خبرهای مشابهی در منابع دیگر هست، ولی داور خودکار هنوز همخوانیشان را بررسی نکرده است.
همین رویداد در منابع دیگر:
- صعود معاملات آتی سهام ایالات متحده همزمان با کاهش قیمت نفت خام؛ بررسی بازارها
- پیروزی لولا در دور دوم انتخابات برزیل؛ نوسان سهام ایالات متحده پیش از انتشار گزارش درآمد شرکتهای فناوری
- بازار سهام: آیا S&P 500 امروز نزولی باز میشود یا صعودی؟
- آتی سهام ایالات متحده پیش از زنگ باز شدن بازار با ارزیابی کاهش قیمت نفت و انتظار برای تصمیم نرخ بهره Fed افزایش یافت
- آغاز رگبار گزارشهای درآمدی؛ همزمان با افت قیمت نفت، معاملات آتی سهام ایالات متحده کمی افزایش یافت - رویترز
- قیمت نفت به بالاترین حد سالانه نزدیک شد: آیا سقوط سهام و رمزارز در راه است؟
- رشد معاملات آتی TSX همزمان با افت قیمت نفت و صعود طلا در پی امیدواری به کاهش تنشها با ایران
منبع: ZeroHedge — متن کامل از فید رسمی منبع، با ترجمهی ماشینی عنوان و خلاصه