نگاهی اولیه به درآمدهای المونتی: «تولید سانگدونگ در حال افزایش، با بارگیری نخستین محموله»
شرکت Almonty Industries، تامینکننده پیشرو تنگستن عاری از مناقشه برای بازارهای غربی، درآمدهای سه ماهه سوم خود را کمتر از انتظارات وال استریت گزارش کرد، اما تحلیلگران بانک آمارکا محمولههای اولیه از معدن سانگدونگ در کره جنوبی را «در حال افزایش مطلوب» و نخستین محموله را بارگیریشده توصیف میکنند. تحلیلگر فلزات و معدن BofA...
First-Take On Almonty Earnings: "Sangdong Ramping, With First Cargo Loaded" Almonty Industries, a leading supplier of conflict-free tungsten to Western markets, reported third-quarter earnings below Wall Street expectations , but Bank of America analysts describe initial shipments from its Sangdong mine in South Korea as "ramping up well" and the first cargo loaded.
BofA metals and mining analyst Lawson Winder wrote in a note on Friday morning that while Almonty reported third-quarter earnings below forecasts, it delivered "substantial earnings improvement QoQ and YoY."
Almonty's flagship Sangdong Tungsten Mine in South Korea is seen as one of the world's largest and highest-grade tungsten deposits . Once fully operational, it is expected to account for over 80% of global tungsten production outside China, addressing the critical supply shortage in the West and supporting the upcoming rearmament supercycle.
Winder said work on Sangdong's second phase is underway , equipment has been ordered, and construction is scheduled to be completed in 2027. He noted that more than 90% of first-phase production is already contracted , providing a solid revenue outlook as the mine ramps up into next year.
"This and a strong balance sheet further de-risks the Sangdong project and positions the company well to execute its growth plans," the analyst said, adding, "ALM has been active on its share buyback program through to this quarter. We maintain our Buy rating given ALM's strong volume growth, relatively low-cost structure, and a solid balance sheet."
He described Almonty as one of two publicly traded Western producers and the only US-listed company in that group, offering investors exposure to elevated tungsten prices and efforts to diversify the West's critical material supply chains away from China.
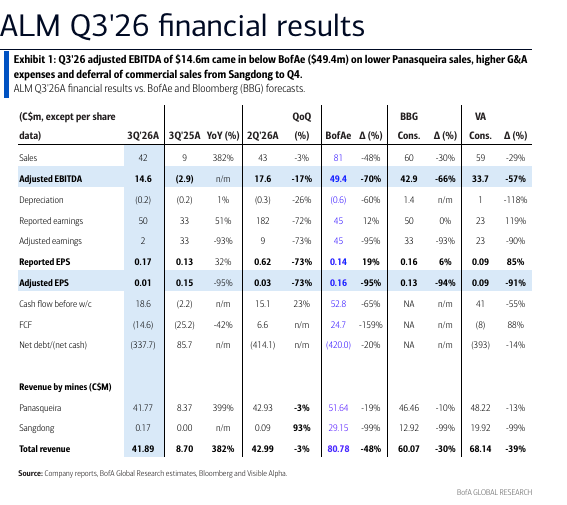
ALM reported Q3'26 adjusted EBITDA of C$14.6 million (m), below BofAe at C$49.4m and Bloomberg (BBG) / Visible Alpha (VA) consensus at $42.9m/C$33.7m. The miss vs BofAe was driven by lower Panasqueira sales (lower grade and timing), higher G&A expenses and the deferral of commercial sales from Sangdong to Q4. While Sangdong achieved concentrate production in September, the first shipment was loaded at the port subsequent to quarter end. Despite lower-than-expected sales and higher royalties, Panasqueira generated a 62% EBITDA margin in Q3 (benefitting of strong tungsten pricing). Per ALM, the Portuguese government intends to reduce the royalty rate to 4.0% (from 19.7%), retroactive from the start of 2026, implying a potential $15m in refunds for 9M'26. Reported Q3'26 EPS at C$0.17 vs. BofAe/BBG/VA at C$0.16/C$0.13/C$0.09, benefitted from $47.9m of non-cash gains on the revaluing derivatives and warrants.
On 24-Aug-26, ALM announced a share repurchase program for up to 14.4m shares, for an aggregate purchase price of up to $300m, over a 36-month period. During Q3'26, ALM repurchased 2.9m shares at $16.58/sh ($67.7m invested) and in Q4-to-date, bought back 0.7m more shares. At quarter-end, ALM's cash position remained solid at C$1.15 billion (bn) and net cash of $338 m vs. cash of C$1.23bn and net cash of $414m at 30-Jun-26. In addition to the share buyback, the build-out of Sangdong Phase 2 through 2027 will be a key capital allocation for ALM in the near-term. We forecast a meaningful inflection higher in free cash flow to over $700m in 2027E (vs. around $100m this year). We forecast Phase 2 contributing from early H2'27E with Phase 1 ramped-up by Q1'27E.
Winder maintained his Buy rating with a 12-month price target of $24 a share.
D.A. Davidson analyst Matt Summerville's first take after earnings:
After the close, ALM reported 3Q26 sales of USD $30M, which was $7M below our estimate, though rose +382% Y/Y, with the entirety of variance attributable to lower head grade and shipment timing. Panasqueira's income from mining operations rose considerably Y/Y to $19M, driven by higher pricing, partially offset by a 13% Y/Y reduction in shipments with $4.3M in deferred revenue recorded during the first week of October (which would effectively all drop to mining income). Sangdong Phase I continues to ramp with its first cargo of tungsten loaded and shipped in October. Our LT thesis remains well intact amid deep primary supply deficits. BUY
Stifel View - waiting period: Quarterly results came in mostly as expected with Panasqueira continuing to be the consistent driver of earnings and no input from Sangdong, yet. Earnings continue to benefit from elevated APT prices even as the price has started to come off record highs – as expected and included in our model (see chart on page 2). Sangdong is now in what CEO Lewis Black described as the "long silence" that follows the commissioning of a new mine as all the kinks are worked out, and the mine ramps to full capacity. We continue to expect Phase I to hit full cadence in 2027 and see our ~C$30m estimate for revenue contribution in 4Q as reasonable but would not sound the alarms at any slippage into 2027. We have made limited changes to our model outside updating for the 3Q results and remain Buy rated but have updated our target price to $18 as we brought our multiple down to 11.5x 2027E EBITDA multiple (12.5x previously).
Almonty, like the broader mining stocks, has been battered in the second half of the year by higher rates and a strong-dollar environment. Weaker commodity prices have also been seen in recent weeks, such as gold tumbling below $4,000 and copper tumbling in London from the $14,500 level to around $13,588.
More broadly, VanEck's REMX rare earth and strategic metals ETF has been halved since summer and retraced much of the run-up sparked early last year by China's restrictions on critical material supplies to the West.
We pointed out earlier on Friday that President Trump's $40 billion critical materials deal push will likely come under the Democratic Party's crosshairs, as miners that accepted government equity and other financing deals will likely face scrutiny.
As we noted in that report, Almonty accepted no government equity investment or other financing deals, which may help it avoid hearings on Capitol Hill next year.
" We've always believed government's place in our business is as a customer, not a shareholder, and look forward to continuing to provide the U.S. and its allies with tungsten to support critical defense and industrial needs ," said Lewis Black, CEO of tungsten miner Almonty Industries.
We continue to favor the " owning the bottlenecks " theme as China restricts critical material supplies to the West. The focus remains on producing miners with conflict-free supply chains outside China that are also entirely independent of US government-backed financing .
As we've also pointed out: The Great Rare Earth Disconnect: Prices Up 23%, Miners Down 28% ...
تا این لحظه منبع مستقل دیگری این خبر را منتشر نکرده است.
بررسی خودکار: مقایسه با خبرهای ۷۲ ساعت اخیر منابع دیگر و اعتبار پایهی منبع؛ جایگزین داوری انسانی نیست.منبع: ZeroHedge — متن کامل از فید رسمی منبع، با ترجمهی ماشینی عنوان و خلاصه